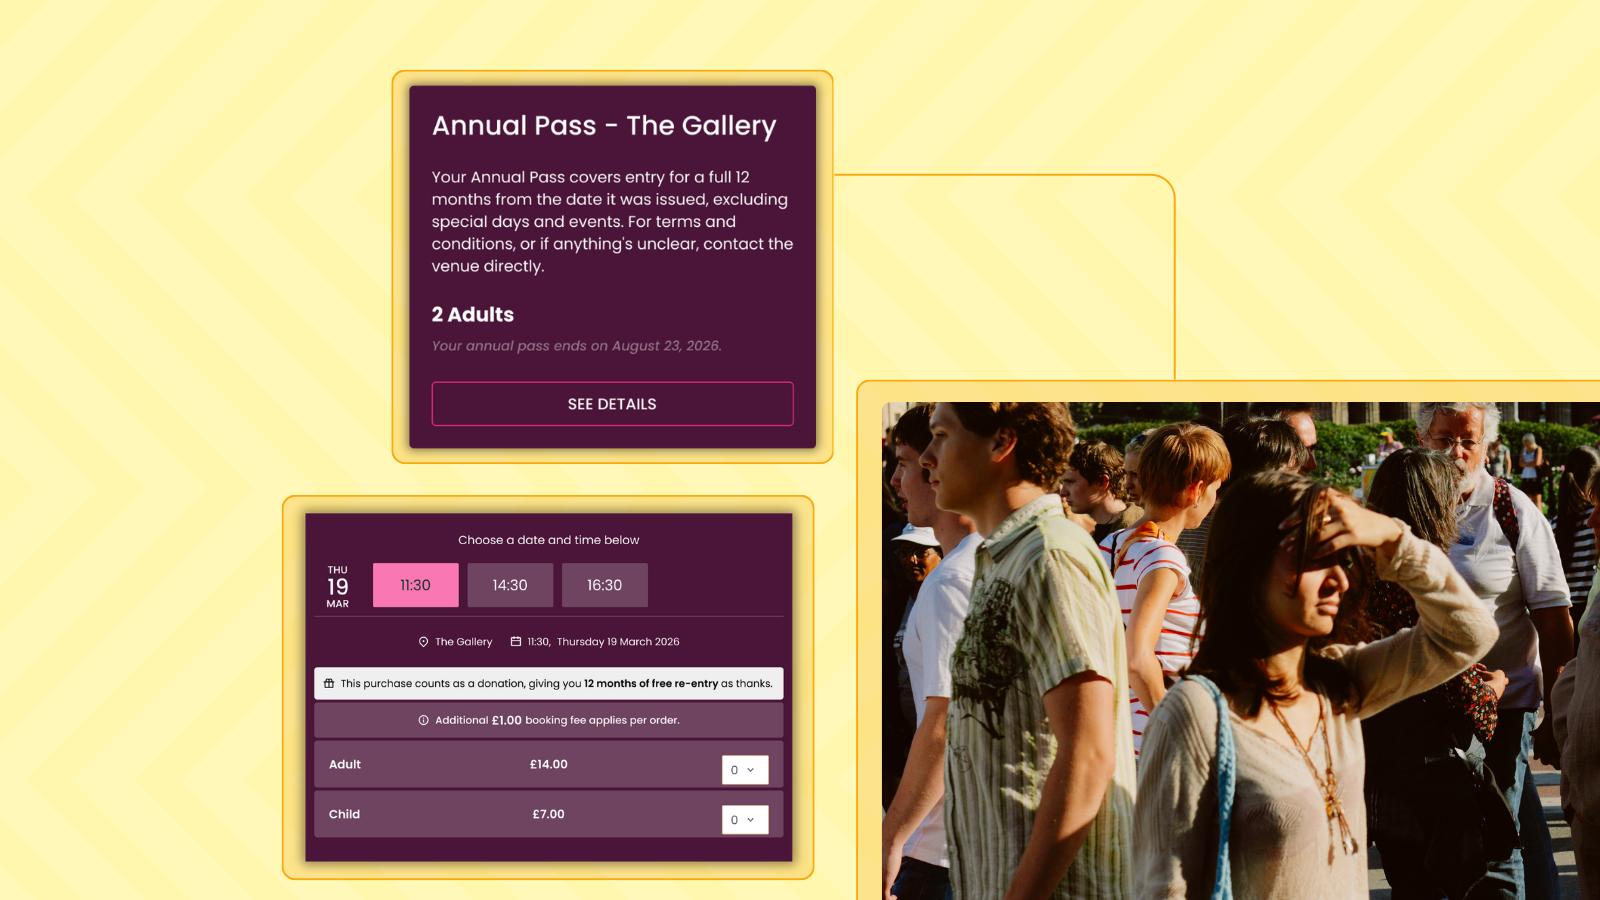
Annual passes, memberships and gift aid: a guide for venues.

Unlock extra venue revenue with Gift Aid-compliant annual passes. Discover HMRC rules, avoid setup mistakes, and see how Ticketsolve handles the mechanics.

Annual passes and memberships bring real benefits to the venues that sell them - and to their bottom line. They provide predictable revenue upfront, and members and pass holders tend to spend more on secondary channels (including F&B and merchandise) during a visit.

For charitable venues, membership and annual pass schemes can, in some cases, also open up an additional revenue stream through Gift Aid. But that's only possible if the scheme is built to meet HMRC's rules.

This guide sets out exactly what you need to do to build a qualifying scheme, the setup mistakes that can disqualify you, and how Ticketsolve can handle the mechanics for you.

The basics

As the name suggests, Gift Aid applies to gifts, not purchases. HMRC rules stipulate that gifts - which qualify for gift aid - are straightforward monetary donations where the donor expects nothing in return. A purchase, which is excluded from gift aid, results in the customer acquiring something- goods, services, a ticket, a service, access to a facility.

According to these rules, if a customer pays to acquire a membership or annual pass, this is legally considered a purchase. However, HMRC provides a concession specifically for charitable heritage and visitor attractions, giving venues two clear ways to structure annual passes in exchange for a donation:

  • Free entry model: One donation grants free admission to the property for the entire year. The full donation qualifies for Gift Aid.
  • Discounted entry model: An initial donation unlocks a discounted ticket price for every visit during the year. Only the initial donation is eligible for Gift Aid, while the discounted entry fees are treated as normal admission charges.

Each individual pass scheme must strictly follow one model - you cannot blend free and reduced-price entry features within the same pass type. For ease of administration and seamless online setup, Ticketsolve recommends choosing one consistent model across your primary venue passes.
When does an annual pass or membership qualify?

To be eligible for gift aid, ensure your scheme meets the following criteria: 

It grants a right of admission for a year or more. The pass has to give the member the right to visit for at least twelve months. If your venue is not open to the public every day, or all year round, that’s fine - but admission must be possible whenever the property is open to the public. The right of admission must apply when non-pass holders or non-members are able to visit - so avoid special members or pass holder days! 

The same deal must be open to everyone, taxpayer or not. The right of admission can’t be dependent on the member or pass holder choosing to Gift Aid the amount of their donation. Everyone must be able to purchase a pass or membership, with exactly the same terms, and at exactly the same price, even if they’re not a UK tax payer or just don’t want to Gift Aid their pass or membership donation. Gift Aid is something the venue claims on top, invisibly to the member - never a condition of the offer.

It buys admission to view property, not a performance. HMRC's admissions relaxation covers the right to view a charity's property: buildings, grounds, collections, artefacts, works of art, and similar, but does not include performance. A pass or membership that provides access to plays, concerts, or shows on this basis, even though the same organisation might be able to provide access to guided tours or exhibitions. This is why many museums, galleries and heritage sites avail of this model, but setting it up is a bit more complicated for theatres or arts centres. 

Just a note: there are additional options to claim Gift Aid on admission fees - notably, if a visitor chooses to add a voluntary donation of at least 10% on top of the standard admission price, the entire amount qualifies for Gift Aid. Find out more in our Gift Aid on Tickets guide.

Want to learn more about our platform?

What might disqualify you from claiming Gift Aid?

Bundling extras into a single headline price alongside admission. If you offer a pass or membership that combines an admission fee alongside other benefits, such as additional classes and or activities, you must advertise the cost of both separately, as you can only claim Gift Aid on the admission fee. 

For example, a membership, advertised at £250, that includes £30 of basic membership plus £220 of classes would not be eligible for Gift Aid. If it was advertised as a membership comprising a £30 annual pass and £220 worth of extras, it would be Gift Aid eligible, but the claim would only apply to the £30 admission fee. 

Personal use of facilities or services. A membership that allows members to avail of discounted or free use of facilities - a café, a car park, members-only events or classes… veers into the territory or buying services, not making a gift, so would make the membership ineligible for Gift Aid. Benefits that do not provide free or discounted access - such as receiving a monthly newsletter, are absolutely fine. 

Providing benefits worth more than statutory limits. If you’d like to provide additional benefits to say thank you to your members or passholders, that’s fine - provided the total value of those benefits stays within HMRC's thresholds.

  • Passes up to £100: The maximum total benefit value is 25% of the donation. For example, on a £50 pass donation, you can offer benefits worth up to £12.50 (such as a £10 cream tea). A £20 afternoon tea would exceed the limit and void your Gift Aid claim.
  • Passes between £101 and £1,000: The maximum benefit limit shifts to £25 plus 5% of the amount over £100. For example, a £150 membership donation has a maximum benefit allowance of £27.50 (rather than 25% / £37.50).
  • Passes over £1,000: The total value of all combined benefits is capped at a maximum of £70.

Refunds. A donation can't be repayable under any circumstances. If the pass terms allow a refund - for a cancelled event, bad weather, a closure - the payment isn't a donation and won't qualify. This is why memberships for charitable venues are exempt from the UK subscription regime under the Digital Markets, Competition and Consumers Act 2024. You can read more about this in our guide.

Specific situations to have in mind

Family passes. A family pass can qualify for the above rule, however the subscription is treated as a gift from one donor - the person who makes the Gift Aid declaration - even though it grants admission to their family too. The right of admission covers the donor and their family whether or not they all visit together, or at the same time. What counts as a family is up to you to define, but the pass has to admit family members only: a pass bought for a coach party or a group of friends won't qualify.

Paying for someone else. Buying an individual pass for another adult - a friend, a parent, a partner (outside of a family pass) can’t be gift aided, as it doesn’t count as a gift to the charity. The exception is a donor's own children under 18, where a pass bought for the child is treated the same as one bought for the donor.

Special events. If you’re running an annual pass or membership scheme, you’re still able to hold a few ticketed events with their own, additional admission charge. HMRC rules allow you to specify up to five days a year on which the pass-holder's free or reduced admission doesn't apply. It’s worth noting events held outside normal public opening hours - such as evening concerts or film nights - don't count towards the five.

VAT is separate. Remember - your normal rate of VAT applies, as there’s no relaxation of VAT rules on admission payments. We’d recommend confirming your position with your finance team or financial adviser before launching your scheme.

How annual passes work in Ticketsolve

Annual passes are coming soon to Ticketsolve, and have been intentionally designed around HMRC guidelines. Key features include:

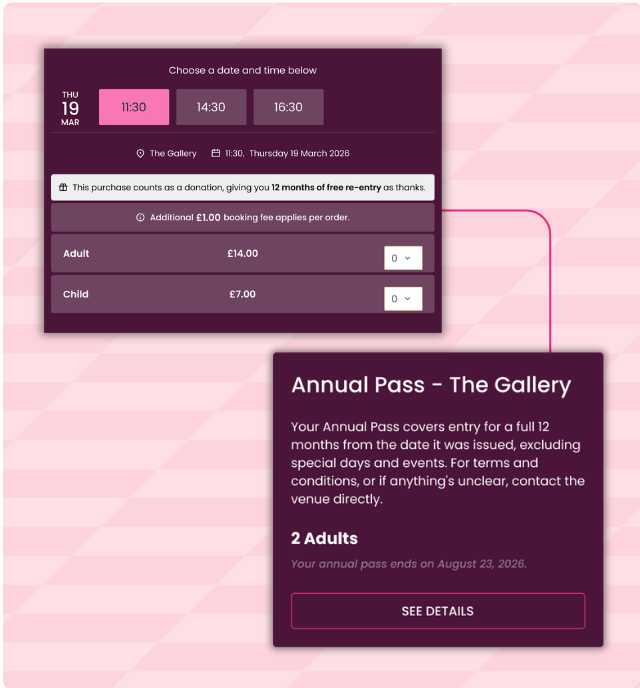
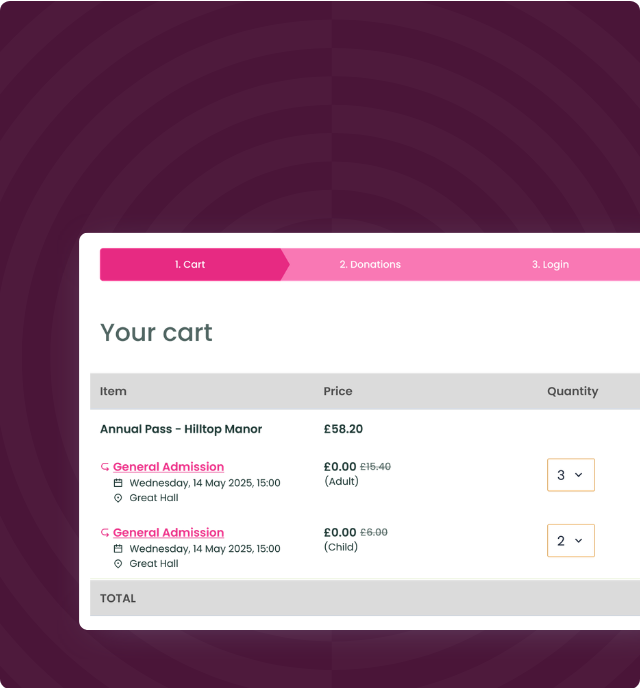
  • Automatic Add-To-Cart: As soon as a customer selects eligible admission tickets online, at the box office, or over the phone, Ticketsolve automatically adds the Annual Pass to their basket.  
  • Automatic Ticket Bundling: Ticketsolve discounts the selected tickets to £0 and rolls their full monetary value directly into the pass price. Because the pass price is dynamically calculated from the initial tickets, a pass must always be purchased alongside admission tickets.
  • One Single Donation: Instead of paying for individual tickets, the customer pays a single pass donation.
  • Exact Return Allowance: The pass grants year-round admission matching the exact quantity and type of tickets bought on day one (e.g., 2 Adults and 1 Child, capped at a maximum of 10 tickets per pass).

Stress-Free Gift Aid Compliance:

  • Integrated Reporting: Pass payments automatically surface in your Donations & Gift Aid reports ready to claim.
  • Optional Claiming: If a customer does not opt in or isn't a UK taxpayer, the pass functions identically. Every customer pays the exact same price.

A well-built annual pass is one of the most effective secondary revenue tools available to a charitable venue, and Gift Aid makes it meaningfully more so. The rules are specific, but are easy enough to if the setup is designed around them from the start: a donation that grants year's admission, open to everyone on the same terms, without any added extras. 

Of course, every venue, and every venue’s annual pass set up, has its specificities. It’s with confirming any queries with HMRC or dedicated experts or advisers before submitting your claim.

Annual passes are soon to be released in Ticketsolve - watch this space for more info, or get in touch to hear more.

Quote icon

Let's start something brilliant together

We’d love to show you how we can help you thrive.

No items found.

Download the Whitepaper

Download now